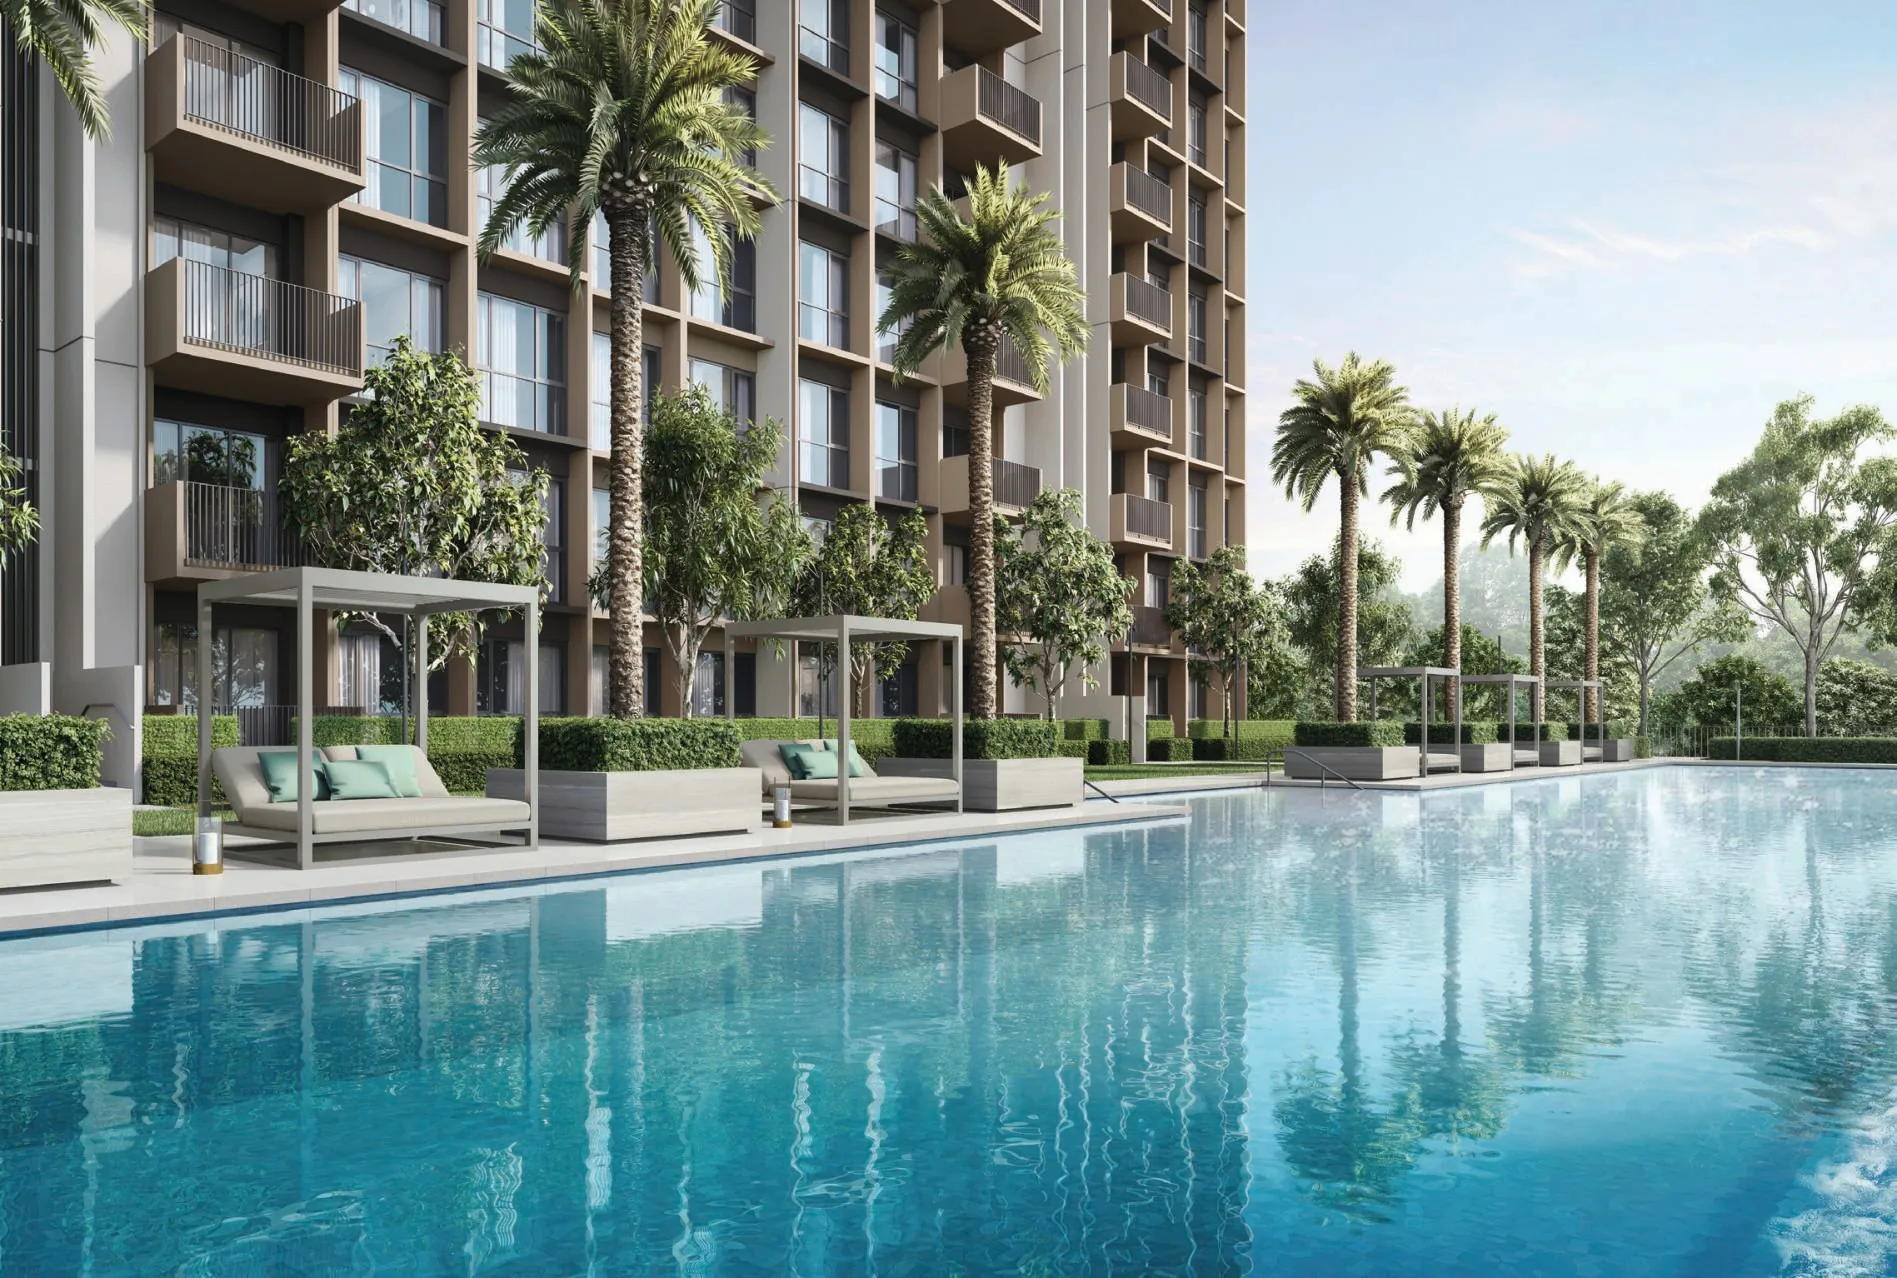
 Artist’s impression
Two ceilings apply at once to a loan on a home at Coastal Cabana. As an executive condominium bought from the developer, it is tested against the mortgage servicing ratio (MSR) of 30% of income as well as the total debt servicing ratio (TDSR) of 55%, and the lower of the two decides the loan. On top of the bank’s tests, HDB’s eligibility conditions decide who may buy.
Coastal Cabana and the Two Ceilings: MSR and TDSR
The MSR caps the monthly repayment on property loans at 30% of gross monthly income; the TDSR caps all monthly debt repayments, the new loan included, at 55%. For most households the MSR binds first. Other debts only start to matter once they exceed a quarter of income, because 55% less those debts falls below 30% only when the debts are more than 25% of income; so clearing a car loan rarely changes how much an EC buyer can borrow.
| Rule | As at October 2026 |
|---|---|
| Mortgage servicing ratio (MSR) | 30% of gross monthly income, property loans only |
| Total debt servicing ratio (TDSR) | 55% of gross monthly income, all debts |
| Interest rate used for both tests | The higher of a 4% floor or the loan’s thereafter rate |
| Variable and rental income | Counted at 70%, after a 30% haircut |
| Joint borrowers | Income-weighted average age |
Source: MAS (mortgage servicing ratio, media release of 11 January 2013; 4% medium-term interest rate floor, media release of 29 September 2022, for options granted on or after 30 September 2022); checked 22 October 2026. Limits can change; confirm with MAS or your bank before signing.
Who Can Buy a Coastal Cabana Home: HDB’s EC Conditions
A new executive condominium is sold under eligibility conditions that HDB sets and checks. They are summarised below; the EC affordability calculator applies the income test and the grant tiers to a household’s figures.
Source: HDB, Executive Condominium eligibility conditions, conditions after buying an EC and resale pages; MND media release of 10 September 2019 (income ceiling for ECs bought from developers); checked 22 October 2026. HDB determines eligibility.
After the purchase
Source: HDB, conditions after buying an EC and resale of an EC; checked 22 October 2026.
The CPF Housing Grant for Coastal Cabana Buyers
Eligible households buying a new executive condominium may receive a CPF Housing Grant for ECs, credited to their CPF Ordinary Accounts. It depends on average gross monthly household income, on citizenship and on whether the household is buying with a housing subsidy for the first time.
| Average monthly household income | First-timer SC/SC | First-timer SC/SPR | First-timer and second-timer SC/SC |
|---|---|---|---|
| $10,000 or less | $30,000 | $20,000 | $15,000 |
| $10,001 to $11,000 | $20,000 | $10,000 | $10,000 |
| $11,001 to $12,000 | $10,000 | Nil | $5,000 |
| $12,001 to $16,000 | Nil | Nil | Nil |
Source: HDB, CPF Housing Grant for executive condominiums (tiers as checked in September 2026). Grant amounts are decided by HDB; confirm the amount for your household with HDB. Second-timer households receive no grant.
Note the gap between the two figures that matter: the grant tapers to nothing at $12,000 a month, while the income ceiling for buying is $16,000. A household can be comfortably eligible to buy at Coastal Cabana and receive no grant at all, so it is worth checking both before a viewing.
Coastal Cabana Loan-to-Value Limits
Alongside the income tests, the loan may not exceed a share of the price that depends on how many housing loans the borrower already has, with a lower limit when the tenure exceeds 30 years or the loan runs past age 65 on the income-weighted average age.
| Outstanding housing loans | Standard LTV | Lower LTV | Minimum cash |
|---|---|---|---|
| None | 75% | 55% | 5% (10% in the lower band) |
| One | 45% | 25% | 25% |
| Two or more | 35% | 15% | 25% |
Source: MAS loan-to-value limits. Limits can change; confirm with MAS or your bank before signing.
Over 30 years, or past age 65.
The loan limit drops and minimum cash on a first loan rises to 10%; the EC calculator keeps the tenure within 30 years and age 65.
In-Principle Approval Before a Coastal Cabana Viewing
Many buyers ask a bank for an in-principle approval before a viewing, sized under the MSR rather than the TDSR. It states how much the bank is prepared to lend on the information supplied, subject to final approval and a valuation, and turns the stamp duty, the booking fee and the cash share into firm figures. Each bank sets its own terms and validity period.
Once the buyer’s own share has been paid, the loan is drawn stage by stage under the payment scheme, and the progressive payment calculator shows the split at every stage.
Request the Coastal Cabana Price List
Coastal Cabana is open for sale. The Sales Concierge replies with the developer’s current price list and the homes still open for selection. Showflat viewings are arranged by appointment through the Sales Concierge.
Sent on request
- The current price list and the homes still open for selection.
- The e-brochure and the floor plans you shortlist.
- A payment schedule and an EC affordability estimate.
- A showflat appointment at a time that suits you.
Request the Price List
No obligation. The Sales Concierge responds personally to every enquiry.
Prefer to speak to someone? Call +65 6200 6220, or send a WhatsApp message to the same number.